
Advertisement
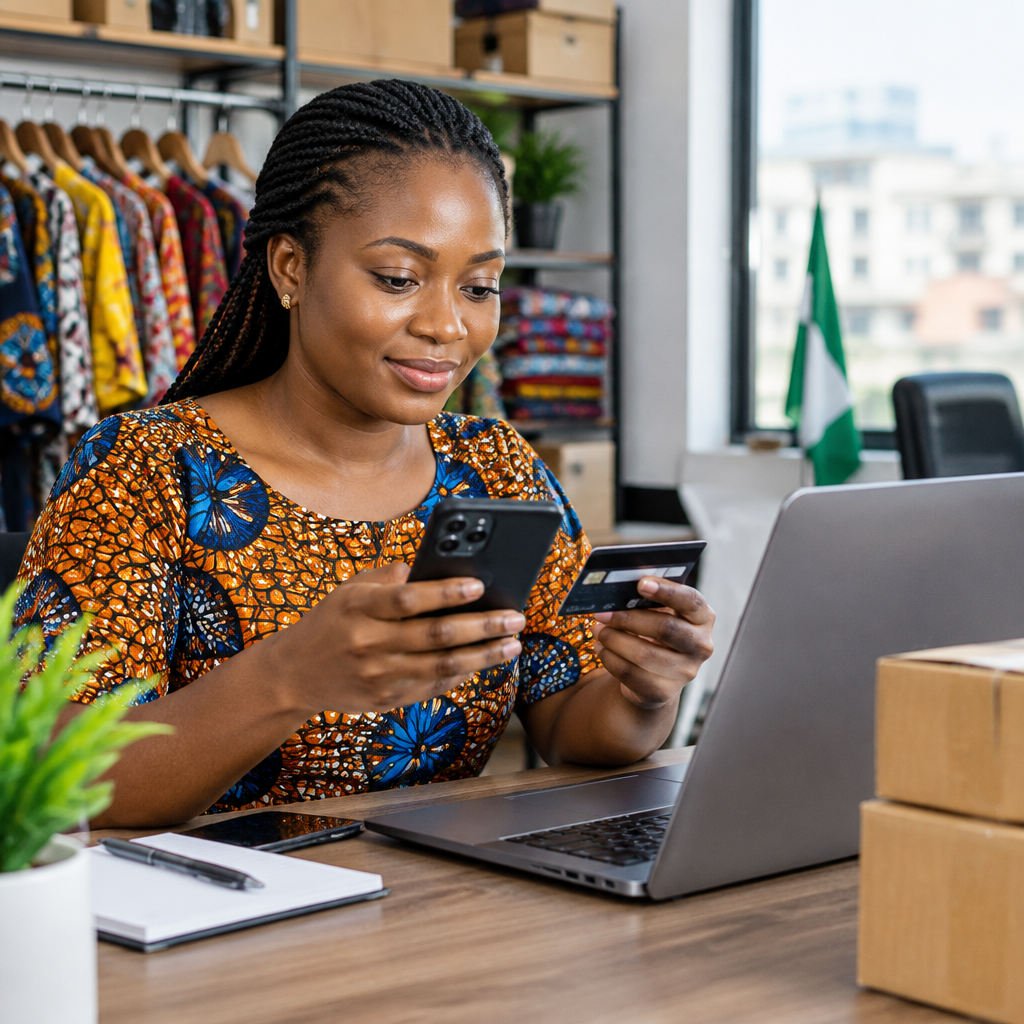
Accepting payments online can help a small business sell beyond its neighbourhood, serve Nigerians abroad and receive payment for products or services without waiting for a bank transfer confirmation. However, convenience also creates risks: fake payment alerts, stolen card details, account takeovers, chargebacks and mistakes caused by sending money to the wrong account.
The safest approach is not to accept every available payment method immediately. Choose a reputable payment provider, separate business money from personal funds, confirm payments independently and limit the sensitive information your business collects.
Advertisement
Table of Contents
Choose a payment method that fits your business
Different businesses need different payment arrangements. An online shop selling clothing may need card and transfer payments, while a web developer or consultant may mainly need invoices and bank transfers. A creator selling a digital product may need a payment page that can automatically confirm successful transactions.
Common options include:
- Bank transfers: Customers send money to a business account. This can be simple, but you must verify the transaction in your account rather than relying on screenshots.
- Payment links: A provider creates a link that you can share through a website, social media or messaging app. This is useful when you do not yet have a full online shop.
- Hosted checkout pages: Customers are redirected to a payment provider’s page to complete payment. The provider handles much of the sensitive payment process.
- Website checkout integration: A developer connects a payment provider to your online shop so customers can pay and receive an automated order response.
- Mobile or QR-based payments: These can be convenient for in-person sales, but staff should still confirm the payment in the business account or merchant dashboard.
For many small businesses, starting with a business bank account and a reputable hosted payment page is safer than trying to store card details or build a payment system from scratch.
Check the provider before opening an account
Do not choose a payment provider only because its advert appeared on social media or because another seller mentioned it in a group chat. Visit the provider’s official website and review its business onboarding requirements, supported payment methods, settlement process, dispute procedure, fees and customer support channels.
Look for clear answers to these questions:
- Does the provider support businesses operating in Nigeria and the customers you want to serve?
- Which currencies and payment methods can customers use?
- How are successful payments displayed and how long can settlement take?
- What happens when a customer disputes a card transaction?
- How can you contact support if a payment is missing?
- What business and identity documents are required?
- Can you export transaction records for bookkeeping?
Requirements, limits and fees can change, so confirm them directly with the provider before relying on a feature or quoting a final cost to customers. Avoid providers that ask you to share your password, one-time password, card PIN or private recovery phrase.
Keep business and personal money separate
Using a personal account for regular business sales makes reconciliation harder and can expose personal transactions to staff or customers. Where possible, use an account or wallet intended for business activity, with access controls that match your team.
Create a simple record for every order containing the customer’s order reference, amount, date, payment status and fulfilment status. Do not store unnecessary card information. A payment reference or provider transaction ID is usually more useful than collecting sensitive payment details yourself.
If you run an online shop, web development service or hosting business, connect each payment to a specific invoice or order number. This reduces confusion when several customers pay similar amounts on the same day.
Secure the accounts that control your payments
Your email address is often the key to resetting a payment account, website account or business bank login. Protect it as seriously as the payment dashboard itself.
- Use a long, unique password for every important account.
- Turn on multi-factor authentication where it is available.
- Give staff the least access they need to perform their jobs.
- Remove access promptly when a worker leaves or changes responsibilities.
- Keep your phone, computer, browser and business applications updated.
- Use a password manager rather than keeping passwords in a notebook or chat.
- Set up account alerts for logins, withdrawals, refunds and other important actions.
Never approve a login request or share an OTP because someone claims to be from a payment company, bank, marketplace or support team. Legitimate support should not need your password, card PIN or authentication code.
Confirm payments before releasing goods or services
A screenshot is not proof that money has reached your account. Fraudsters can edit screenshots, alter SMS messages or send a fake bank alert. Confirm payment by checking the official bank application, account statement, merchant dashboard or another trusted channel that you open yourself.
Use a simple workflow:
- Give the customer an order or invoice reference.
- Ask the customer to pay through the approved account or payment link.
- Check the payment status in your own dashboard or bank account.
- Match the amount and reference with the order.
- Only then release the product, activate hosting, begin a project or deliver a digital item.
Be especially careful with overpayment requests. A scammer may claim to have paid too much and ask you to refund the difference before the original payment is properly confirmed.
Reduce fraud with clear business rules
Write down how your business handles refunds, cancellations, failed payments, duplicate payments and disputed transactions. Display the important parts before checkout. Customers should understand what they are buying, the total price, delivery timing and how to request help.
For higher-risk orders, consider additional checks that do not expose private information. For example, you may delay fulfilment until a payment is settled, manually review unusually large orders or contact a returning customer through details already on your order record.
Do not ask customers to send card numbers, PINs, passwords or OTPs through WhatsApp, email or social media. If identity information is genuinely necessary for a service, explain why it is needed, collect only what is required and protect access to it.
Recognise common payment scams
Small businesses in Nigeria may encounter scams through social media, messaging apps, marketplaces and email. Warning signs include:
- A customer pressures you to release goods before the payment appears in your account.
- Someone sends a link to “activate” your merchant account and asks for login details.
- A supposed bank or provider representative requests an OTP or PIN.
- A customer asks you to pay a fee before receiving a payment or refund.
- The payer’s name, amount or transaction reference does not match the order.
- You are asked to move the transaction to an unfamiliar platform without a clear reason.
When something feels unusual, pause the transaction. Contact the payment provider through its official website or application, not through a phone number or link supplied by the suspicious message.
What to do after a suspicious transaction
Preserve relevant evidence, including the order reference, messages, transaction details and time of the incident. Do not delete the conversation or continue arguing with the suspected fraudster. Contact your bank or payment provider through an official channel and ask what protective action is available.
If your account may have been accessed, change the password from a trusted device, end other sessions, review recent activity and secure the email account connected to it. If customer data may have been exposed, document what happened and communicate honestly with affected customers where appropriate.
A practical starting setup
A new Nigerian online seller does not need a complicated system on day one. A sensible starting arrangement could include a dedicated business account, one reputable payment provider, a basic invoice or order-number system, multi-factor authentication and a daily reconciliation routine.
As sales grow, the business can add website checkout, staff permissions, automated receipts and accounting tools. Security should grow alongside convenience: every new integration creates another account, password and possible route into the business.
The safest online payment system is one your business can understand and monitor. Use a trusted provider, protect account access, verify money independently and keep sensitive information out of chats and spreadsheets. These habits help a small business serve customers online without treating every payment as a leap of faith.
Advertisement
