Advertisement
Advertisement
If you buy, sell, receive or transfer cryptocurrency, keeping a clear record of each activity can save you from serious confusion later. Your exchange account may show some transactions, but it may not contain every detail you need to understand your profit, loss, fees, deposits, withdrawals or tax position.
A good record-keeping system should answer simple questions: What asset did you acquire? When did you acquire it? How much did you pay? Where did it go? What did you receive when you sold or exchanged it? Which fees were charged? Can you prove the transaction came from your account?
Advertisement
This guide explains a practical way to store digital-asset records securely. It is written for beginners, including Nigerians managing assets across local bank accounts, international platforms, wallets and peer-to-peer services. It is educational information, not tax, legal or investment advice. Tax treatment can depend on your country of residence, the type of activity and the rules in force when you report.
Table of Contents
What counts as a digital-asset record?
Keep records for more than just completed sales. The following information may become useful when reviewing your activity:
- Purchases made with naira, another currency or a different digital asset
- Sales, swaps and conversions between assets
- Deposits and withdrawals from exchanges
- Transfers between your own wallets and platforms
- Cryptocurrency received as payment, rewards, gifts, airdrops or compensation
- Trading, network and platform fees
- Dates, times, quantities and transaction identifiers
- Wallet addresses and the platform or service involved
- Bank statements, payment receipts and peer-to-peer trade evidence
A transfer between two wallets that you control may not be the same as a sale, but it should still be recorded. Without a note explaining the transfer, you may later mistake it for income or an unexplained deposit.
Use a transaction ledger as your main record
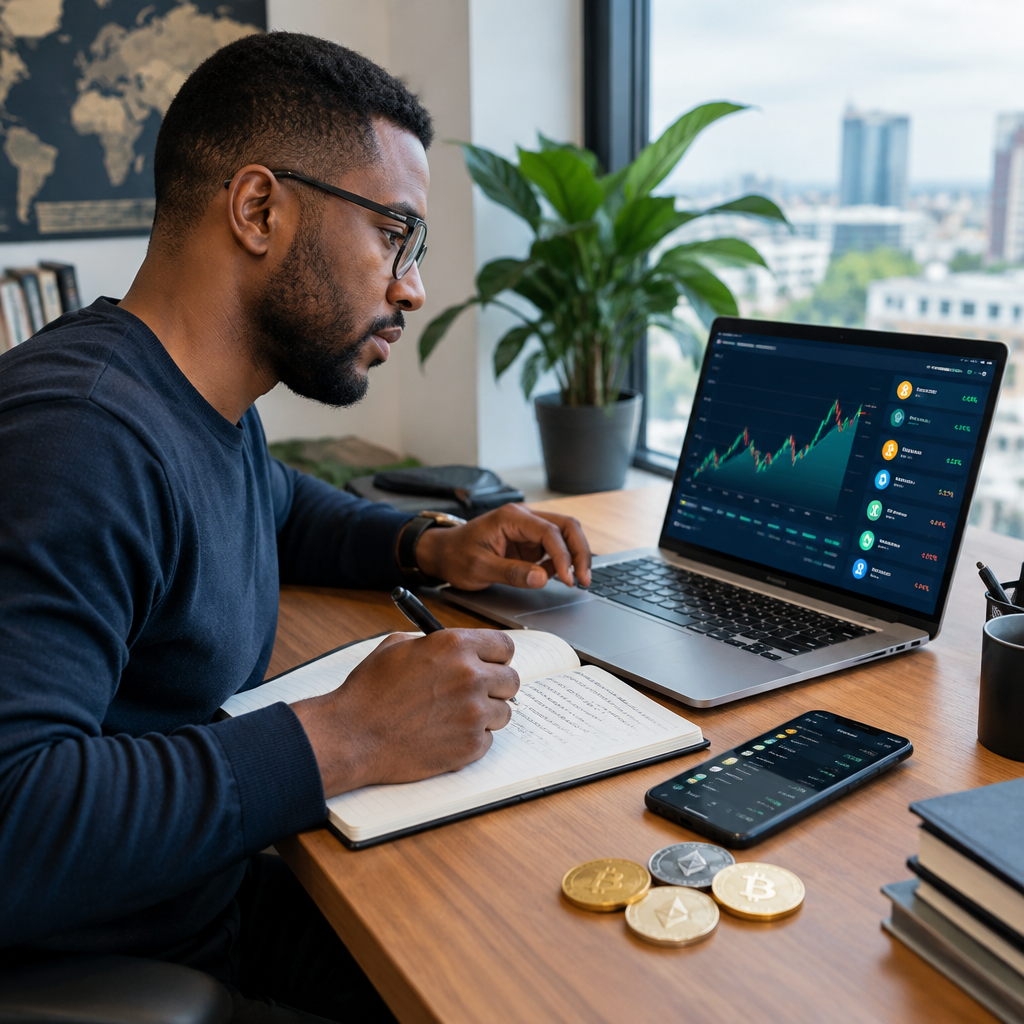
A spreadsheet is usually enough for a beginner. You can use a spreadsheet application on a computer or phone, but keep a backup in a separate secure location. Create one row for each transaction rather than combining several activities into one monthly total.
Useful columns include:
| Column | What to record |
|---|---|
| Date and time | The date and time shown by the platform or wallet |
| Type | Buy, sell, swap, deposit, withdrawal, reward, gift or transfer |
| Asset sent | The asset and quantity leaving your account |
| Asset received | The asset and quantity entering your account |
| Value and currency | The stated value and currency used for the transaction |
| Fees | Trading, withdrawal, network or other charges |
| Platform or wallet | Where the transaction took place |
| Transaction ID | The blockchain hash or platform reference, where available |
| Notes | The reason for the activity and any unusual details |
Use consistent names for assets and transaction types. For example, do not label one transaction “BTC buy” and another “Bitcoin purchase” if you later plan to filter the sheet by category. Consistency makes the record easier to review.
Separate personal tracking from tax evidence
Your personal tracker helps you understand your holdings and performance. Tax evidence has a different purpose: it helps demonstrate what happened and how you calculated the figures you reported or supplied to a professional.
For personal tracking, you may want to record your current holdings, average acquisition cost, portfolio allocation and notes about your goals. For tax-related documentation, retain original statements, receipts, invoices, payment confirmations and relevant correspondence rather than relying only on a calculated summary.
Do not delete an original exchange export after editing it. Save the untouched file separately, then create a working copy for cleaning or analysis. If a spreadsheet formula changes a number, you should still be able to trace that number back to the original record.
Collect records from every place you use
Many incomplete records come from tracking only one exchange. Make a list of every service or wallet that has held your assets, including:
- Centralised exchanges
- Peer-to-peer marketplaces
- Mobile and desktop wallets
- Hardware wallets
- Decentralised applications
- Payment services and bank accounts used for deposits or withdrawals
Download account statements or transaction histories at regular intervals. If a service allows you to export a CSV file, save it with a clear filename such as ExchangeName_Transactions_2025-01-to-2025-03.csv. Do not assume an old report will always remain available in the same format.
For blockchain transactions, save the transaction ID and a link or reference that allows you to verify it on the relevant blockchain explorer. A blockchain record can confirm that a transfer occurred, but it may not explain why you made it or establish the value you used for your own reporting. Add a note and retain the related payment evidence.
Store files securely without losing access
Digital-asset records can contain sensitive information about your finances. Protect them as carefully as you protect bank statements.
- Use a strong, unique password for the storage account.
- Enable multi-factor authentication, preferably with a security key or authenticator app where suitable.
- Encrypt sensitive files or store them inside a reputable encrypted storage service.
- Keep at least one backup in a separate location.
- Do not store wallet recovery phrases, private keys, PINs, passwords or one-time codes in the same folder as ordinary records.
- Do not email unencrypted files to yourself or share them through public links.
- Review sharing permissions after sending documents to an accountant or adviser.
Your transaction spreadsheet should never contain a wallet seed phrase or private key. A records folder explains what happened; it must not provide access to your assets.
A simple monthly workflow
A short monthly routine is easier than trying to reconstruct years of activity later.
- Export: Download transaction histories from each exchange and wallet service that provides them.
- Reconcile: Compare deposits and withdrawals with your bank or payment records.
- Classify: Label each item as a purchase, sale, transfer, reward, gift, fee or another appropriate category.
- Check balances: Compare the ledger with the balances shown on your platforms and wallets.
- Investigate differences: Look for missing fees, duplicate rows, reversed transactions or transfers between your own accounts.
- Archive: Save original exports and supporting documents using a consistent folder and filename system.
For example, if you move Bitcoin from an exchange to your personal wallet, record the withdrawal, the network fee and the receiving wallet. Add a note saying that both wallets belong to you. Later, this explanation can prevent the transfer from being confused with a sale or external payment.
Common record-keeping problems
Relying on screenshots only
Screenshots can show a balance or confirmation, but they are difficult to search and may omit fees, transaction IDs or historical context. Keep them as supporting evidence, not as your complete system.
Recording only profitable trades
Losses, fees and unsuccessful transactions can affect the overall picture. Record every relevant transaction, not only the ones that produced a gain.
Mixing currencies without a note
If you use naira, US dollars and cryptocurrency in the same spreadsheet, identify the currency for every value. Do not silently convert amounts using an unexplained rate. Note the source and date of any conversion used for your calculations.
Ignoring small transactions
Small rewards, network fees and frequent conversions can accumulate. If an activity is relevant to your tracking or reporting, include it rather than relying on memory.
When to ask for professional help
Consider speaking with a qualified tax professional familiar with digital assets if you trade frequently, receive cryptocurrency for work, operate a business, use decentralised finance, manage assets across countries or cannot reconcile your records. A professional will need accurate source documents, not just a final portfolio screenshot.
Rules can differ depending on where you live, your tax residence and the nature of the transaction. Nigerian readers should avoid assuming that guidance from another country automatically applies to them. Confirm important obligations with an appropriate Nigerian tax or legal professional and keep evidence supporting your interpretation.
The practical takeaway
Good digital-asset record keeping is a repeatable process: record each transaction, preserve original evidence, separate personal transfers from sales, protect the files and back them up. Start with the accounts and wallets you use today, then work backwards through older activity. A simple, consistent ledger is far more useful than a complicated system that you stop maintaining.
Advertisement