Advertisement

Advertisement
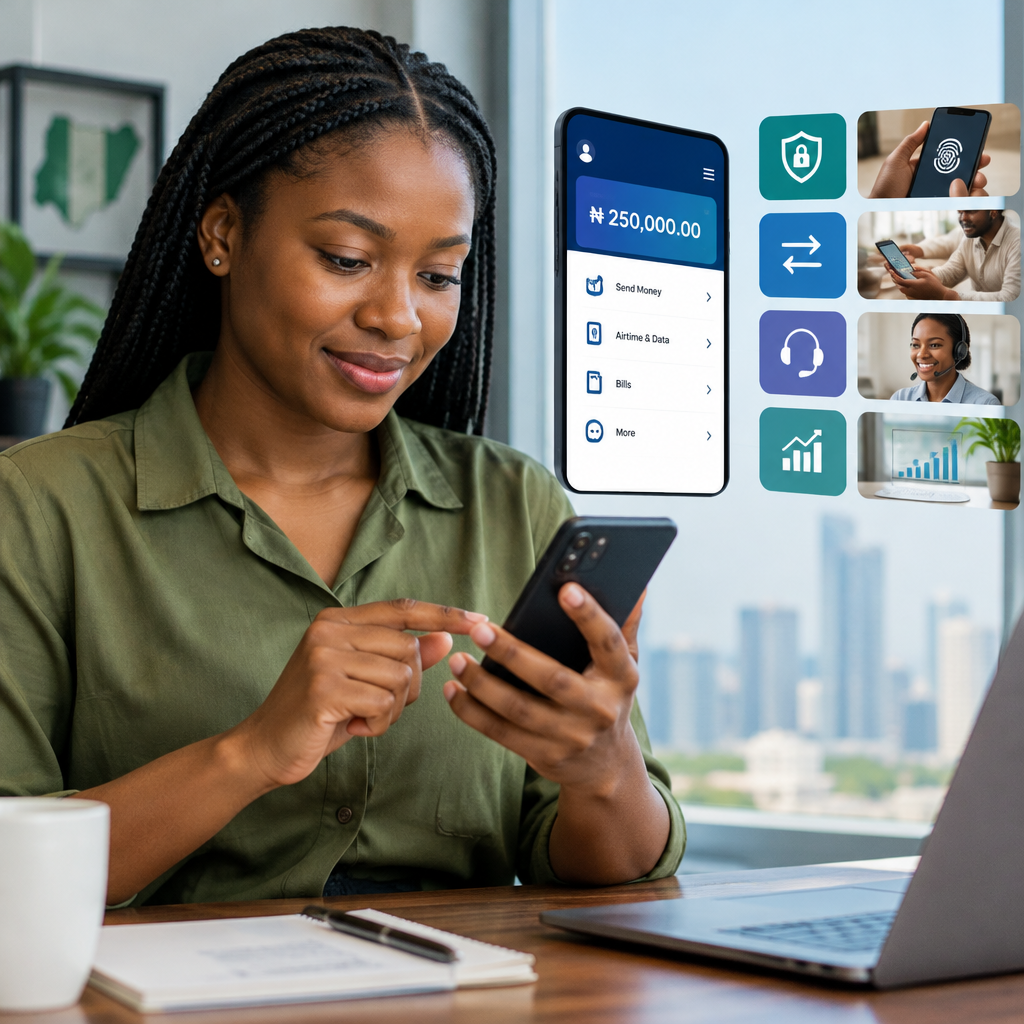
Choosing a digital banking app is not only about finding the one with the most attractive design. The right app should help you receive money, transfer funds, pay bills and monitor your account safely, even when you are using a phone or internet connection that is not perfect.
For customers in Nigeria, this comparison matters because digital banking may involve bank transfers, card payments, airtime and data purchases, bill payments and connections to other financial services. Students, workers, entrepreneurs and Nigerians living abroad may also have different needs. A person receiving a salary may prioritise reliability, while a small business owner may care more about transaction records and payment notifications.
Advertisement
Table of Contents
Start with the services you actually need
Before comparing logos, colours or promotional offers, write down the transactions you expect to make. This prevents you from choosing an app because of a feature you may never use.
- Sending and receiving bank transfers
- Paying for airtime, data, electricity or other services
- Using a physical or virtual debit card
- Receiving payments from customers or clients
- Saving money or tracking spending
- Accessing an account while travelling or living outside Nigeria
- Downloading statements for budgeting, school, work or business records
Some apps are connected to a traditional bank, while others are provided by fintech companies or payment institutions. Their account-opening process, available products, dispute procedures and regulatory arrangements may differ. Read the provider’s official terms before depositing significant funds.
The essential features to compare
1. Account security and control
Security should be the first comparison point. Check whether the app supports a strong password or passcode, device locking, biometric login and alerts for transactions. It should also give you a way to freeze a card or restrict an account if your phone or card is lost.
Look for clear controls that let you review active sessions, manage linked devices and change your security details. A good app should not require you to share your PIN, password or one-time password with a staff member. No legitimate support agent should need those secrets.
Also check how the provider communicates. Fraudsters often impersonate banks through social media, calls, text messages and messaging applications. Use contact details inside the official app or on the provider’s verified website rather than relying on a phone number sent by a stranger.
2. Transfer options and transaction confirmation
Compare how easily you can transfer money to accounts at other banks, save beneficiaries and repeat common payments. The app should display the recipient’s details for review before you confirm a transaction.
After a transfer, you should receive an in-app confirmation and, where supported, a downloadable receipt or transaction reference. This reference can help when a recipient has not received money or a debit appears without the expected credit.
Do not judge an app only by whether a transfer button exists. Check the complete process:
- Can you identify the recipient before sending money?
- Is the amount and destination easy to review?
- Does the app show a clear success, pending or failed status?
- Can you find the transaction later in your history?
- Is there a practical way to report a failed or disputed transaction?
3. Reliability on ordinary connections
An app can have many features but still be frustrating if it frequently freezes, logs you out or fails during a payment. If you rely on mobile data or use an entry-level phone, check whether the app opens quickly and remains usable on your device.
Customer reviews can reveal recurring problems, but they should not be treated as proof on their own. Complaints may relate to temporary outages, individual account issues or misunderstanding of a feature. Look for patterns and compare them with the provider’s official service updates and support responses.
It is sensible to keep a backup payment method. No digital service is guaranteed to work at every moment, so avoid placing all your available money in one app if you cannot access another way to pay for essentials.
4. Fees and limits
Examine the fees that apply to your normal activities rather than focusing only on a free account-opening offer. Potential charges may relate to transfers, card delivery, cash withdrawals, card replacement, currency conversion, bill payments or inactivity.
Limits are equally important. An account may restrict daily transfers, card spending, cash withdrawals or incoming payments until identity information has been completed. Find out what happens when you reach a limit and whether increasing it requires additional verification.
Fees and limits can change. Treat information displayed inside the app or on the provider’s current official fee schedule as more reliable than an old social media post, blog article or promotional video.
5. Customer support and dispute handling
Support becomes most important when money is missing, a card is compromised or an account is locked. Check whether the provider offers in-app support, email, telephone or another documented channel. More channels do not automatically mean better service; what matters is whether the process is clear and produces a reference number.
Before using an app regularly, find out how to report:
- An unauthorised card or account transaction
- A transfer marked successful by the sender but not received by the beneficiary
- A cash withdrawal that failed but was debited
- A mistaken transfer or payment
- A lost phone, SIM or card
Never delay reporting a suspicious transaction while trying to resolve it through informal online comments. Keep screenshots, dates, amounts and transaction references, but remove passwords, PINs, OTPs and full card details before sharing any evidence.
Useful features for different customers
| Customer need | Features worth checking |
|---|---|
| Student or young worker | Simple transfers, airtime and data payments, spending alerts, low-cost card access and easy account recovery |
| Small business owner | Payment notifications, statements, transaction search, separate business tools and reliable support for disputed payments |
| Freelancer or person receiving money from abroad | Supported currencies or services, transparent conversion information, identity requirements and withdrawal options |
| Frequent traveller | Card controls, international-use settings, security alerts and a clear process for replacing a lost card |
| Beginner using mobile finance | Plain-language instructions, accessible support, clear confirmation screens and strong fraud warnings |
Do not overlook verification and privacy
Digital financial services may ask for personal information to verify identity and comply with applicable requirements. The exact documents and onboarding conditions can vary by provider and account type. Read the official requirements before starting, and provide information only through the legitimate app or website.
Check the privacy policy in practical terms. What information does the service collect? Does it request access to contacts, messages, location or other phone functions? An app should explain why permissions are needed. Avoid installing banking applications from unknown websites or modified app files.
A simple comparison method
Create a short table with three or four services and score each one from one to five for security controls, transfer convenience, reliability, fees, support and features relevant to you. Give greater weight to the categories that affect your daily life.
Then test the app cautiously. Install it from the official app store or provider website, complete the legitimate verification process, and try low-risk functions before committing larger funds. Confirm that notifications arrive, transaction history is understandable and support can be reached.
The best digital banking app is not necessarily the one with the longest feature list. It is the service that fits your regular payments, explains its charges, protects access to your account and gives you a credible way to resolve problems. Compare the full customer experience—from registration to dispute handling—before deciding where to keep and move your money.
Advertisement
