Advertisement

Advertisement
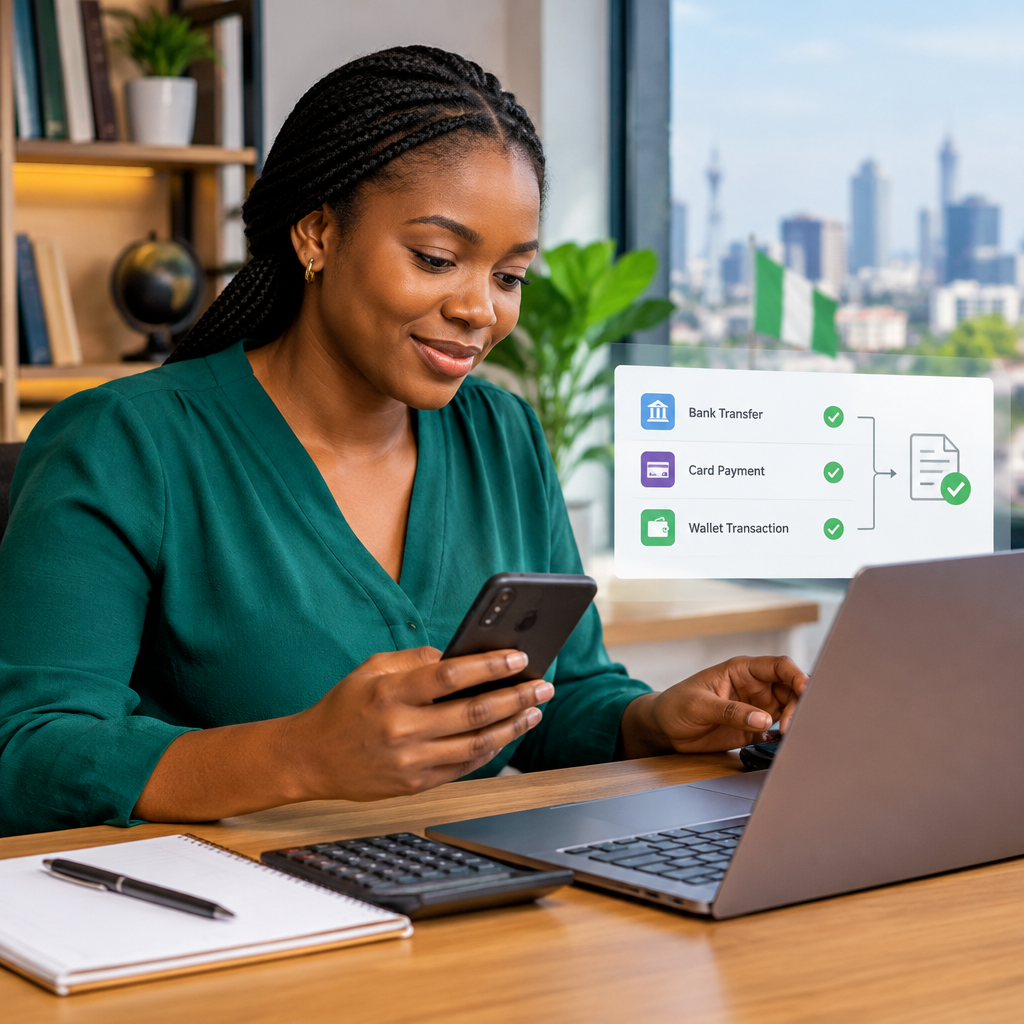
When customers pay by bank transfer, card, payment link or digital wallet, the money may arrive through different channels and at different times. Without a reliable way to match each payment to a sale, a business can easily mark an unpaid order as settled, chase a customer who has already paid or lose track of its actual income.
Digital payment reconciliation is the process of comparing your sales records with records from your bank, payment processor or wallet provider. The aim is simple: every completed sale should have a corresponding payment, and every payment should have a clear explanation.
Advertisement
This is useful for Nigerian small businesses that sell through social media, websites, online marketplaces, physical shops or a combination of these channels. It is also important when a business receives many small transfers and cannot depend on memory or screenshots alone.
Table of Contents
What payment reconciliation means
Reconciliation involves comparing two records for the same period:
- Your sales record: invoices, receipts, orders or booking records showing what customers were charged.
- Your payment record: bank statements, payment processor reports, card settlement reports or wallet transaction histories showing what was received.
A transaction is matched when key details agree, such as the amount, date, customer or order reference. A transaction that appears in one record but not the other requires investigation.
For example, if your order book shows a customer paid ₦35,000 for a service but your bank record shows ₦34,300, the difference may be a processing fee, a partial payment or an error. You should not mark the records as fully matched until you understand the difference.
Why reconciliation matters to a small business
Good reconciliation is more than an accounting exercise. It helps you make better daily decisions and protect your business from avoidable losses.
- It confirms which orders are paid. This reduces the risk of releasing goods or starting work based only on an unverified payment claim.
- It identifies missing payments. A customer may have used the wrong account details, entered an incorrect reference or abandoned a payment that was not completed.
- It explains differences. Fees, refunds, reversals and settlement delays can make the amount received different from the amount charged.
- It improves cash-flow planning. You can distinguish sales that were recorded from money that has actually reached your account.
- It creates better records. Clear records are useful when preparing management reports, reviewing expenses or handing information to an accountant.
The information to record for every transaction
You do not need expensive software to begin. A well-designed spreadsheet can work for a small operation if it is updated consistently.
For each sale, record:
- an internal order or invoice number;
- the date of the sale;
- the customer’s name or business identifier, where appropriate;
- the product or service supplied;
- the amount the customer was expected to pay;
- the payment method or channel;
- the payment reference or transaction ID;
- the amount received;
- any fee, refund or adjustment;
- the matching status; and
- notes about unresolved issues.
Avoid storing sensitive information such as a customer’s PIN, password, one-time password, full card security details or banking login. A payment reference is useful for reconciliation; a secret authentication code is not.
A practical reconciliation workflow
1. Choose a fixed review period
Reconcile daily if your business handles frequent payments. A weekly review may be sufficient for a lower-volume business, but waiting several months makes errors harder to trace. Use a defined period, such as Monday to Sunday, and keep the same approach each time.
2. Gather all relevant records
Collect your sales register and the corresponding bank or payment-provider report. If you use more than one channel, keep them separate at first. For example, review bank transfers, card payments and payment-link transactions independently before combining the results.
3. Match using more than the amount
Two customers can pay the same amount on the same day. Use several details together: amount, date, reference, customer name, order number and payment channel. A screenshot from a customer may help you investigate, but it should not replace confirmation in your own account or provider dashboard.
4. Mark each item clearly
Use simple statuses such as Matched, Partially matched, Pending, Refunded, Reversed or Needs investigation. Do not delete an unmatched transaction. Keeping it visible creates an audit trail and makes follow-up easier.
5. Investigate the exceptions
For every unmatched item, ask a specific question. Was the payment sent to the correct account? Is the provider still processing it? Was a fee deducted? Was the order cancelled? Did someone enter the wrong amount or reference? Record the answer and the action taken.
6. Confirm the closing balance
At the end of the review, compare the opening balance, money received, refunds, fees and other movements with the closing balance shown by the financial institution. This provides a second check that your transaction list is complete.
How to handle common differences
| Difference | Possible explanation | What to check |
|---|---|---|
| Received amount is lower | Processing fee, bank charge or partial payment | Provider statement, fee breakdown and customer payment amount |
| Payment appears late | Settlement delay, weekend or processing issue | Transaction status and value date |
| Payment appears twice | Duplicate customer payment or duplicate entry | References, order records and refund history |
| Sale has no matching payment | Unpaid order, failed payment or wrong account | Order status and account transaction history |
| Payment has no matching sale | Unrecorded order, advance payment or unidentified transfer | Reference, payer details and customer communications |
A payment that cannot be identified should not automatically be treated as profit. Keep it in a suspense or investigation category until you know what it relates to.
Example: matching a social-commerce order
Imagine a small online seller records an order for goods priced at ₦50,000. The customer pays through a payment link. The provider report shows ₦50,000 received, a service fee deducted and a lower net settlement sent to the seller’s bank account.
The correct reconciliation is not to change the sale to the lower bank deposit. Instead, record the full customer payment, record the provider fee separately and match the net settlement to the provider report. This preserves both the value of the sale and the cost of accepting the payment.
If the customer sends only a screenshot and the provider still shows the transaction as pending or failed, keep the order pending. Confirm the final status through the relevant account or dashboard before releasing goods or treating the sale as complete.
Controls that prevent avoidable errors
- Give each order a unique number and ask customers to include it where the payment channel permits.
- Separate business and personal transactions where possible.
- Assign one person responsibility for recording sales and another for reviewing them if the business is large enough.
- Save provider reports in dated folders rather than relying on a live dashboard alone.
- Record refunds and reversals when they happen, not weeks later.
- Restrict access to financial records and protect spreadsheets with appropriate account security.
- Never approve a payment based solely on an edited image, message or caller’s claim.
When to use accounting or payment software
A spreadsheet may be enough when transaction volume is low and one person can review every entry. Consider dedicated accounting or reconciliation software when you have multiple payment channels, recurring invoices, several staff members, stock connected to orders or frequent refunds.
Before choosing a tool, check whether it can import the records you actually receive, preserve transaction references, separate fees from sales, handle partial payments and restrict staff access. A sophisticated tool with poor data connections may create more work than a simple, consistent process.
Key takeaway
Reconciliation works best when it is a routine, not an emergency exercise. Record each sale with a reference, compare it with an independent payment record, investigate every difference and keep sensitive credentials out of your business files. Whether you use a spreadsheet or dedicated software, the goal is the same: know what was sold, what was received, what was deducted and what still needs attention.
Advertisement
