
Advertisement
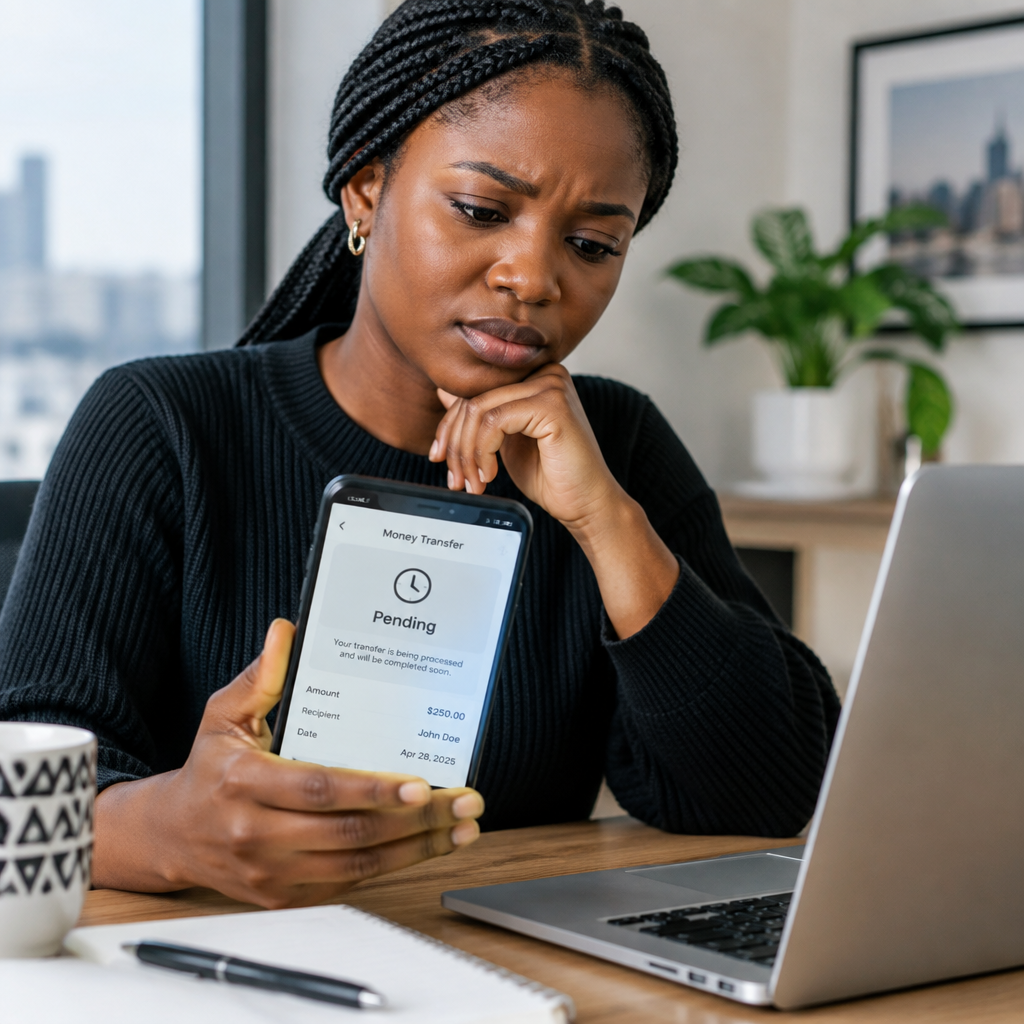
A pending bank transfer can be worrying, especially when money has already been deducted from your account or the recipient is waiting for payment. However, “pending” does not always mean the transfer has failed or that your money is lost.
The transaction may still be moving through your bank’s system, an interbank payment network or the receiving bank. Before reporting it, check the transaction status, account details, available balance and any message from your bank. These simple checks can help you avoid duplicate transfers and provide better information if you need support.
Advertisement
Table of Contents
What does “bank transfer pending” mean?
A pending transfer is a payment that has been initiated but has not yet received a final status. The bank may still be processing, verifying or attempting to complete it.
Depending on the payment method, a pending transaction may mean:
- The transfer instruction was received but has not been completed.
- The sending bank has debited or reserved the money while waiting for confirmation.
- The receiving bank has not yet acknowledged the payment.
- The transaction requires an additional security or compliance check.
- A temporary network or service interruption has delayed the status update.
Do not assume that a pending transfer is automatically successful. Equally, do not immediately send the money again. A second payment could create a duplicate transaction if the first one later goes through.
First, confirm the exact status
Open your bank’s official mobile app, internet banking platform or transaction notification and read the status carefully. Banks may use different terms, including pending, processing, successful, failed, reversed or declined.
Check the transaction history rather than relying only on an SMS or a notification preview. A message may be delayed, duplicated or incomplete. Look for:
- The transaction date and time.
- The amount and currency.
- The recipient’s name, account number or other identifying information.
- The transaction reference or session ID.
- The current status and any error message.
- Whether the amount was actually deducted, reserved or still available.
Save the reference number, but do not publish it publicly. It can help the bank trace the payment when you contact support.
Check whether the money left your account
A pending transfer may appear in your history before the final debit is completed. Compare your current balance with the transaction details, but remember that an available balance and a ledger or account balance may not always update at the same time.
If the money has not been deducted and the transfer remains pending, avoid repeatedly pressing “send” or starting several new transfers. Close and reopen the official app, then check whether the status changes. Do not keep retrying if your bank warns that the first request may still be processing.
If the amount was deducted, do not assume the recipient has received it. Ask the recipient to check the correct account and recent transaction history, not just their SMS alerts.
Confirm the recipient details
Review the account number, bank name, recipient name and amount. A wrong account number can send money to another customer, while a mismatch in details may cause the transfer to fail or remain unresolved.
If you notice an error, contact your bank promptly through an official channel. Do not wait for the recipient to resolve it on your behalf. Banks may have different procedures for transfers sent to an incorrect account, and recovery may not be automatic.
For future transfers, confirm the recipient’s details before entering your PIN or one-time password. For a large or important payment, consider sending a small test amount first when appropriate.
Check for a temporary service problem
Transfers can be delayed by problems affecting the sending bank, receiving bank, payment network, mobile app or internet connection. A weak connection may also leave the app showing an old status after the request has already been submitted.
Try these safe checks:
- Confirm that you are using the bank’s official app or website.
- Check your internet connection and sign in again only through the official platform.
- Review the bank’s in-app alerts or service notices.
- Check the transaction history after a short interval rather than making another payment immediately.
- If possible, ask the recipient to check their account directly.
Do not download an unfamiliar “bank support” app or follow a link sent by a stranger claiming to fix the transfer.
Consider the type of transfer
Not all transfers move in the same way. A transfer between two accounts at the same bank may follow a different process from an interbank transfer. Payments made through a banking app, USSD service, card-linked wallet or another financial platform may also have different confirmation and reversal procedures.
International transfers can involve additional processing stages, currency conversion and intermediary institutions. A pending status may therefore last longer than a local transfer. The relevant bank or service provider should explain the expected process, but avoid relying on unofficial social media claims about completion times.
Weekends, public holidays, maintenance periods and cut-off times can also affect when a payment is processed. These factors do not prove that a transfer will fail, but they may explain why a status has not changed immediately.
When should you contact the bank?
Contact your bank when the pending status lasts longer than the timeframe the bank provides, when the recipient has not received the money after the expected processing period, or when the amount was deducted without a clear outcome.
You should also contact the bank immediately if:
- You did not authorise the transfer.
- Your account was charged more than once.
- The recipient details were incorrect.
- The transfer involves suspected fraud or a scam.
- Your account is blocked or the transaction is connected to a security warning.
Use the phone number on your bank card, official website or official mobile app. You can also visit a branch if that is the bank’s available support route. Never use a number supplied by an unknown person in a comment section or unsolicited message.
Information to prepare before reporting
Support will usually need enough information to locate the transaction. Prepare:
- Your name and the account or profile connected to the transfer.
- The transaction date and approximate time.
- The amount and transfer type.
- The recipient’s bank and account details, where appropriate.
- The transaction reference, session ID or receipt.
- Screenshots showing the status, with sensitive information hidden where possible.
- A clear explanation of what happened and what outcome you need.
Do not send your card PIN, online banking password, one-time password, full card details or account recovery codes. A legitimate bank representative should not need these secret credentials to trace a transfer.
What not to do while waiting
- Do not make another transfer simply because the first one is pending.
- Do not share your PIN, OTP, password or verification code with anyone.
- Do not click links from people promising to release or reverse the money.
- Do not delete transaction notifications or reference details.
- Do not assume a screenshot proves that a transfer was completed.
For payments to a seller, landlord, school, agent or service provider, rely on the bank’s confirmed transaction status and the recipient’s account confirmation—not only a payment screenshot.
A simple decision guide
| What you see | What to do |
|---|---|
| Pending and money not deducted | Wait briefly, check the status again and avoid repeating the transfer. |
| Pending and money deducted | Keep the reference, ask the recipient to check and contact the bank if it does not resolve within the stated timeframe. |
| Failed or reversed | Confirm whether the money has returned before trying again. |
| Successful but recipient cannot see it | Share the official reference and ask both parties’ banks to trace the payment. |
| Unauthorised or suspicious | Contact the bank immediately through an official channel and secure the account. |
The safest next step
Start by confirming the status, amount, recipient details and transaction reference. Give the payment time to update without sending it again, then contact the bank when the delay exceeds its stated timeframe or when there is a risk of fraud, duplication or incorrect details.
For Nigerians managing everyday payments online, keeping accurate records and protecting confidential banking information are just as important as knowing how to report a delay. A pending transfer needs careful verification—not panic, repeated payments or private details shared with strangers.
Advertisement
